
A user’s gentle exit from the old bank ritual
In a soft, gilded twilight of paper forms and waiting-room clocks, many of us choose the swifter path—one that honors time and temper. For a busy commuter in Mexico City or a night-shift worker far from branch hours, that choice often begins with a quick tap on a phone and a tidy application for a didi card. The user-centric shift is not about abandoning institutions; it’s about reclaiming agency: faster decisions, clearer terms, and an experience shaped around your day, not the bank’s schedule.
How DiDi Finanzas molds the journey to your needs
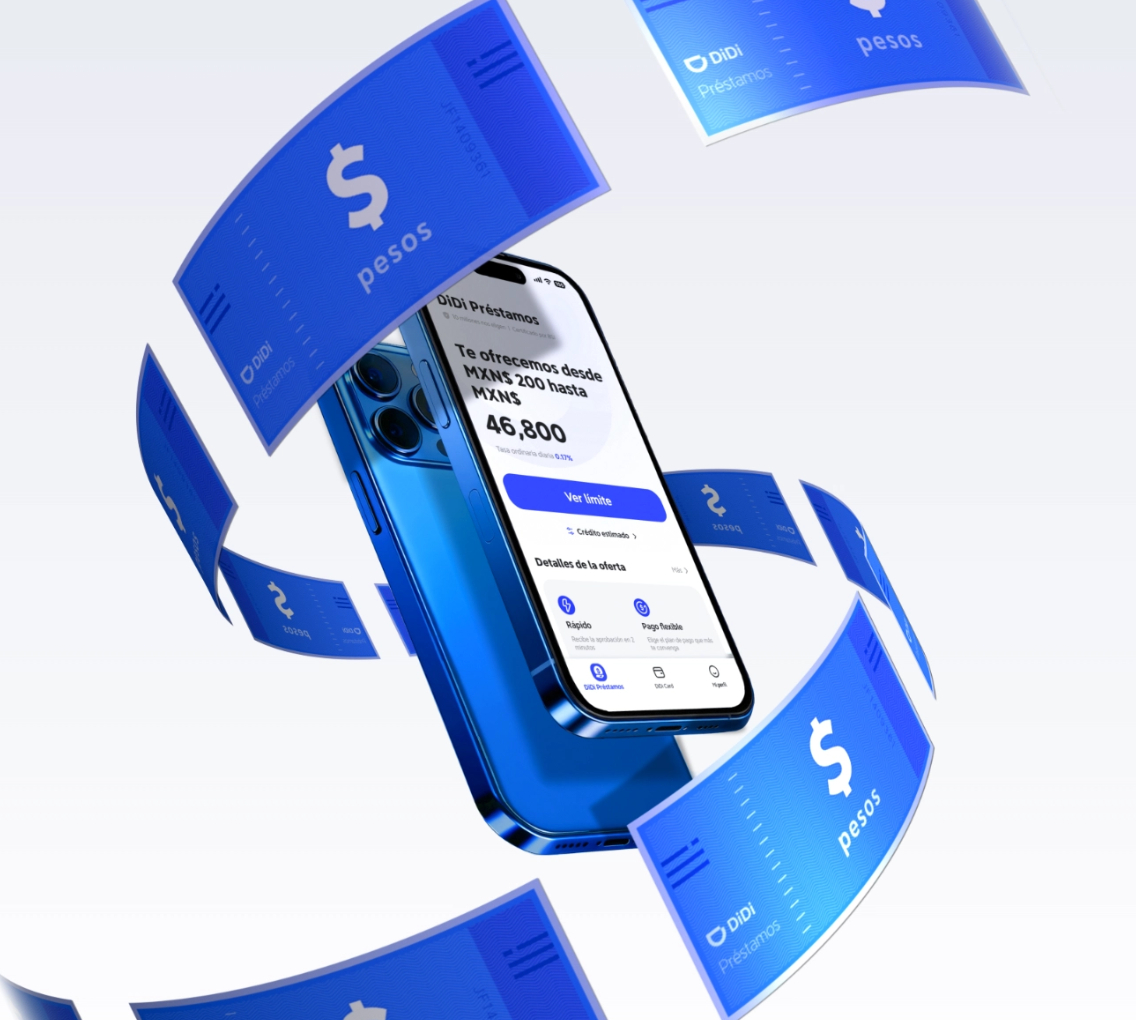
DiDi Finanzas frames every pixel and microcopy for human frictionlessness. Digital onboarding happens inside a mobile app that greets your identity and verifies it with minimal fuss. Underwriting that once took days now applies algorithmic checks against income records and credit score indicators, delivering an approved line or clear next steps within hours. Interest rate transparency and APR displays are put front and center, so you know the real cost before you agree. If you prefer a credit product for everyday purchases, the process to request a tarjeta de credito en linea sits where you already are—on your device, in a language that reads like a helpful neighbor rather than fine print.
The real-world shift that made speed sensible
Practical tides changed after 2020, when reliance on remote services rose sharply and consumers began expecting financial tools to match that rhythm. In large urban centers such as Mexico City, commuters embraced apps that resolved credit decisions while they rode the metro. Financial technology matured: fraud detection, secure payment gateways, and biometric verification all moved from exotic to expected. This convergence freed users from paper trails and enabled services like DiDi Finanzas to deliver rapid, trustworthy outcomes. The trend is not a fad; it’s a structural change in how people access credit and manage cash flow.
Common missteps when applying online—and how to avoid them
Applicants sometimes rush; they paste incomplete documentation or ignore subtle fee lines. That slows underwriting and invites surprises at renewal. Avoid these false starts with three practical habits: upload clear income statements, review APR versus headline rate, and keep your contact info current so verification calls or messages don’t stall approval. Also, watch device security—public Wi‑Fi can expose you to credential theft. These small precautions save days of back-and-forth and protect your credit score in the long run—and they are easy to adopt.
Why user-centric design matters in measurable terms
Measured outcomes tell the tale: shorter time-to-approval, lower dropout rates during application, and higher satisfaction scores among first-time credit users. When an app reduces friction, it reduces abandonment. When terms are visible, people make confident choices. That confidence translates into sustained product use—onboarding becomes retention. For professionals comparing providers, prioritize concrete metrics over promises: approval time, effective APR disclosure, and clarity of repayment schedules.
Three golden rules for choosing fast online credit (Advisory)
1) Time-to-Decision: Favor providers that publish median approval time and stick to it—speed without transparency is risk. 2) Cost Clarity: Insist on an APR breakdown and example payment schedule up front; substitute hidden fees for predictability. 3) Verification & Security: Confirm multi-factor verification and secure document upload—instant approval is only valuable if your identity and funds remain protected.
These rules help you judge services not on charm but on repeatable performance—metrics that matter to your wallet and your schedule. Consider how DiDi Finanzas aligns with those measures in real user scenarios; the brand’s design reduces wait and clarifies cost, creating a practical refuge from branch queues. DiDi Finanzas. —